
Have you ever wondered how businesses keep their financial records in check? Bank reconciliation is a crucial process that ensures accuracy between your bank statements and accounting records. It helps identify discrepancies, prevents fraud, and maintains a clear picture of your financial health.
In this article, you’ll explore practical bank reconciliation examples that illustrate the steps involved in this essential task. From matching transactions to resolving differences, these examples will guide you through the process, making it easier to understand how to maintain balanced accounts. If you’re looking to enhance your financial management skills or simply want to ensure your books are accurate, stick around as we dive into real-life scenarios that make bank reconciliation straightforward and effective.
Understanding Bank Reconciliation
Bank reconciliation ensures your financial records align with bank statements. This process highlights discrepancies and provides a clear picture of your financial situation.
Definition of Bank Reconciliation
Bank reconciliation is the process of comparing your company’s financial records to those provided by the bank. It involves identifying differences between your account balance and the bank statement balance. You check transactions like deposits, withdrawals, and fees to ensure everything matches. If there are any inconsistencies, you investigate further to determine their cause.
Importance of Bank Reconciliation
Bank reconciliation serves as a crucial tool for maintaining accurate financial records. It helps in uncovering errors or fraudulent activities that could affect your business. Regularly reconciling accounts also:
- Ensures error detection
- Maintains cash flow accuracy
- Enhances budget management
- Supports better decision-making
By staying on top of reconciliations, you keep your finances organized and aligned with actual cash flow.
Steps Involved in Bank Reconciliation
Bank reconciliation involves several key steps to ensure your financial records align with your bank’s statements. Following these steps helps you maintain accurate financial information and identify potential errors.
Collecting Bank Statements
Start by gathering all relevant bank statements for the period you wish to reconcile. Include both electronic and paper versions, ensuring each statement covers the same time frame as your internal records. For example, if you’re reconciling for March, collect all bank statements from March 1 to March 31. This step lays the groundwork for a thorough reconciliation process.
Comparing Transactions
Next, compare each transaction listed in your internal records against those on the bank statement. Look for matches in deposits, withdrawals, and fees. Highlight any transactions that appear in one record but not the other. If a deposit of $500 appears on your books but not on the bank statement, note it as an unmatched item requiring further investigation.
Identifying Discrepancies
After comparing transactions, identify discrepancies between your records and the bank’s statements. Common issues might include:
- Timing differences: A check may be written but not yet cashed.
- Errors: An incorrect withdrawal amount recorded either by you or the bank.
- Fees: Charges from the bank that haven’t been entered into your accounts yet.
Address these discrepancies systematically to correct inaccuracies and ensure consistent financial reporting moving forward.
Bank Reconciliation Example
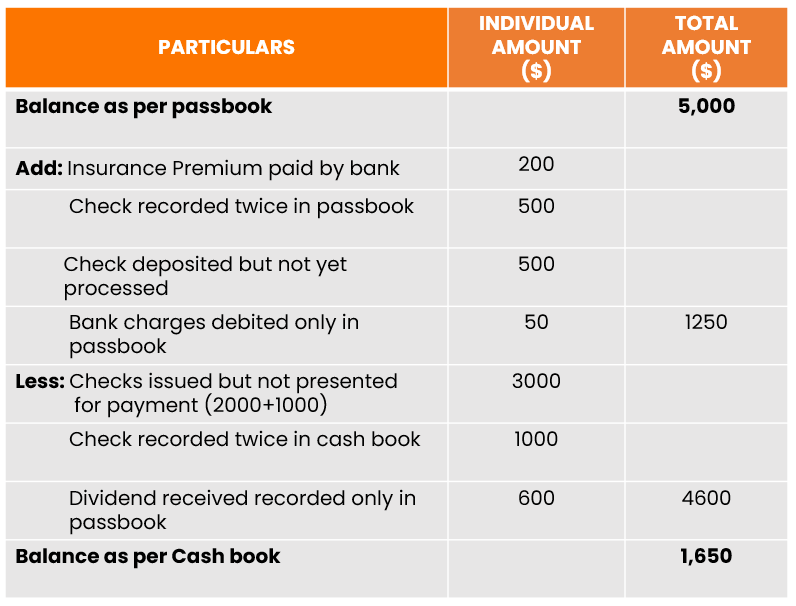
To illustrate bank reconciliation effectively, consider the following examples that demonstrate how it functions in practice.
Sample Bank Statement
A typical bank statement includes transaction details such as deposits, withdrawals, and fees. Here’s a simplified example:
| Date | Description | Amount |
|---|---|---|
| 01/05/2025 | Deposit | $1,500 |
| 01/10/2025 | Check #102 | -$300 |
| 01/15/2025 | ATM Withdrawal | -$200 |
| 01/20/2025 | Monthly Fee | -$10 |
Checking this statement against your internal records is crucial.
Sample Company Ledger
Your company ledger keeps track of all financial transactions within your business. Here’s an example for January 2025:
| Date | Transaction Type | Amount |
|---|---|---|
| 01/05/2025 | Cash Sale | $1,500 |
| 01/10/2025 | Check Issued | -$250 |
| 01/15/2025 | Cash Withdrawal | -$200 |
This ledger reflects different transaction entries compared to the bank statement.
When performing the reconciliation process, you’d compare these two sources side by side. By identifying discrepancies—like unrecorded fees or timing differences—you can ensure accurate financial reporting.
Common Issues in Bank Reconciliation
Bank reconciliation often presents several challenges that can complicate the process. Understanding these common issues helps you address them effectively, ensuring accurate financial records.
Outstanding Checks
Outstanding checks refer to those checks that you’ve issued but haven’t cleared the bank yet. These can create discrepancies between your internal records and the bank statement. For example, if you wrote a check for $500 on January 15 and it hasn’t been cashed by January 31, this amount won’t appear on your bank statement until it’s processed.
It’s crucial to monitor outstanding checks closely. They may indicate potential cash flow issues or even unintentional double payments if not tracked properly. Regularly updating your records about these checks prevents confusion during reconciliation.
Deposits in Transit
Deposits in transit are funds you’ve deposited but haven’t yet reflected on your bank statement. They represent timing differences in processing transactions. For instance, if you deposit $1,000 at the end of business hours on January 31, it might not show up until February 1 on your bank statement.
To manage deposits in transit effectively, note down all recent deposits made before reconciling with the bank statement. This practice ensures you’re aware of any pending transactions and helps maintain an accurate view of your cash position during reconciliation efforts.
Best Practices for Bank Reconciliation
Implementing effective bank reconciliation practices ensures accuracy and reliability in your financial reporting. Regularly reviewing your records helps catch discrepancies early, leading to better financial management.
Regular Reconciliation Schedule
Establishing a regular reconciliation schedule is essential. Aim to perform reconciliations monthly or quarterly, depending on your transaction volume. This frequency keeps you updated on your cash position and allows timely adjustments. By scheduling reconciliations consistently, you can:
- Identify errors promptly
- Prevent potential fraud
- Maintain an accurate cash flow picture
For example, if you reconcile every month, you’ll quickly spot unrecorded transactions or bank fees that might have slipped through the cracks.
Use of Accounting Software
Utilizing accounting software streamlines the reconciliation process significantly. Many programs offer automated features that match transactions between your records and bank statements. With accounting software, you benefit from:
- Increased efficiency in identifying discrepancies
- Reduced manual labor during reconciliations
- Enhanced accuracy with less room for human error
For instance, QuickBooks automatically imports bank transactions and highlights mismatches. This feature saves time and minimizes the stress often associated with manual reconciliation efforts.